What to know about the difference between level and decreasing term cover
Thinking about the difference between level and decreasing term cover
What works well
- Decreasing term matches a repayment mortgage cheaply.
- Level term suits needs that do not shrink, like family income.
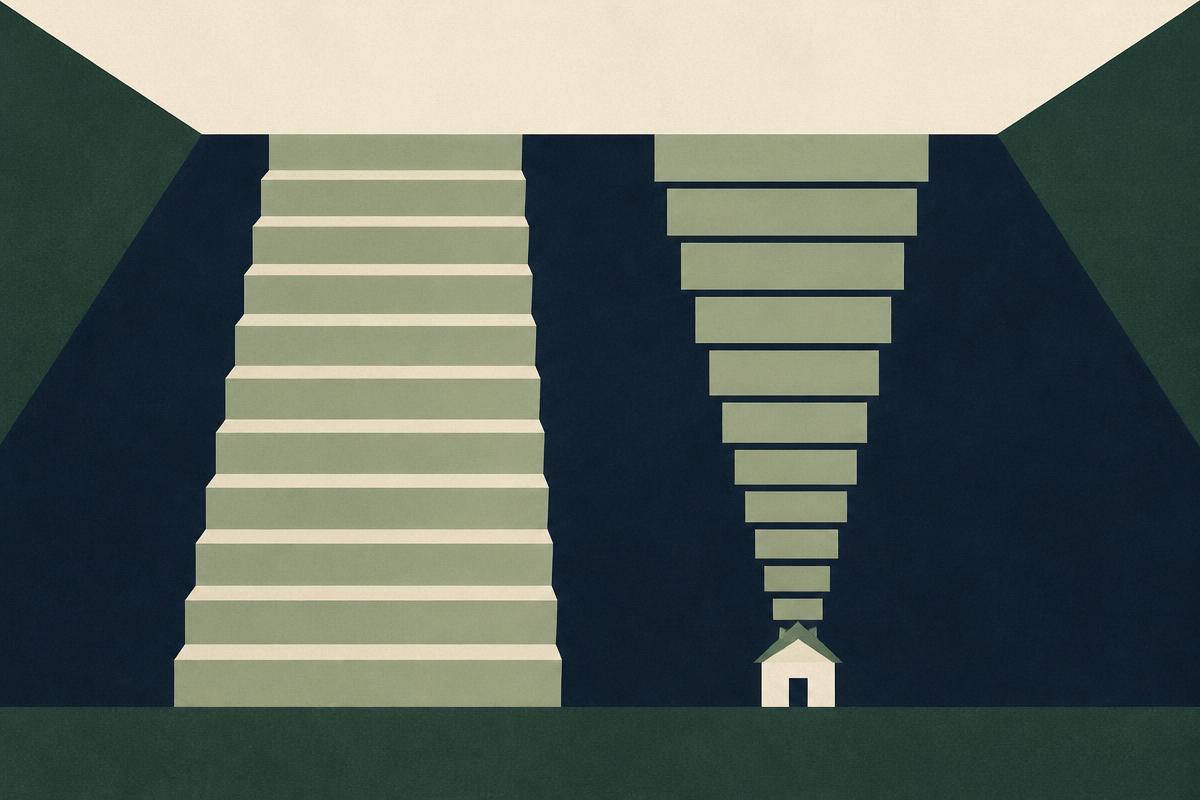
- The structure choice is visible in the illustration before you buy.
What to watch
- The decrease rate may not match your actual mortgage rate.
- Decreasing cover leaves nothing over once the mortgage is cleared.
- A level sum loses real value to inflation over long terms.
A fixed promise versus a shrinking one
A level term policy promises the same sum in year one as in the final year, which suits obligations that do not shrink: family income, childcare costs, an interest-only mortgage. A decreasing term policy promises a sum that falls on a set schedule, designed to shadow a repayment mortgage as monthly payments erode the balance.[2][3] The design assumption matters: the policy’s decrease rate assumes a mortgage interest rate, and if your actual mortgage rate runs higher, the cover can fall faster than the debt — a gap worth checking on the policy illustration.[2] For anything other than a repayment mortgage, level cover is usually the honest structure, because most family needs do not shrink on a schedule. Inflation also works on a level sum over a long term, which is why some policies offer an increasing or index-linked option at higher cost. The assumed decrease rate appears on the insurer’s own policy illustration, not in any published market table.
If the cover is for a repayment mortgage, ask for the policy’s assumed decrease rate and compare it with your actual mortgage rate before buying. The FCA’s conduct rules require the seller to give you appropriate information about the policy before you buy, so ask for the illustration then.[1] Whatever the specifics of the difference between level and decreasing term cover, the discipline that protects your family is always the same: get the insurer’s position in writing, keep the documents with the policy, and make sure the people who would claim know the policy exists and where the paperwork lives.
Related guides
- What life insurance is and how it works
- What moves the price of life insurance
- If a claim goes wrong: do life insurance policies pay out?
- Trusts, tax and the estate: life insurance in trust
Looking at cover with PremierPMI
PremierPMI is a specialist private medical insurance broker and the publisher of The Health Guide. If you want to talk through what this means for your own cover, you can start there.
Or, if you would rather start here, send an enquiry and PremierPMI will contact you.
Common questions
When does level term cover make more sense than decreasing term cover?
Why is decreasing term life insurance usually cheaper than level term?
How can a decreasing term policy end up leaving a shortfall against a mortgage?
Sources and methodology
- [1] Financial Conduct Authority. “ICOBS: Insurance Conduct of Business (FCA Handbook)”. View source(opens in a new tab)Primary source
- [2] Aviva. “Level term vs decreasing term life insurance”. View source(opens in a new tab)Primary source
- [3] Which? Money. “Term life insurance explained”. View source(opens in a new tab)Primary source
We cite primary sources wherever possible. Read about our sourcing methodology.
Ilana Eldad
Corporate PMI Specialist, PremierPMI
- ACCA-qualified
- Corporate and SME scheme specialist
Ilana oversees business health insurance schemes for the corporate and SME team, guiding employers from initial quotes through claims and renewal. ACCA-qualified, she applies that financial background to reducing premiums and advising on tax-deductibility, and runs the largest corporate portfolio at PremierPMI.
Read full profile
Muhammad Junaid
Digital Marketing Executive, PremierPMI
- Digital marketing and search
- Financial promotions compliance review
Junaid leads digital marketing — search, content distribution and measurement — working with the editorial and advisory teams so that every campaign points to real, compliant guidance. He reviews anything published under the brand against the same fair, clear and not-misleading standard as the rest of the site.
Read full profile