Switching in five steps
Try these NHS options first
Before paying for private treatment, check whether the NHS can treat you sooner at no cost. In England, you have a legal right to choose where you are referred for many first appointments [5], and you may be able to move to a provider with a shorter wait. If your treatment is unlikely to start within 18 weeks of referral, the NHS Constitution gives you the right to ask for a suitable alternative provider [2] [3]. Independent hospitals sometimes treat NHS patients, free to them [8].
The NHS website explains what to do if you are worried about your wait, including contacting the hospital and then your integrated care board [4]. Our guides to patient choice and your rights while waiting walk through both.
| Option | What it can do | Cost to you |
|---|---|---|
| Patient choice (England) | Move to a provider with a shorter wait | Free |
| 18-week right | Ask to be offered an alternative provider | Free |
| Independent hospital for NHS care | Treatment in a private setting, NHS-funded | Free |
| Private treatment | Treatment at a time you choose | You or your insurer pay |
Self-pay or insurance
If you decide to go private, the next question is how to pay. Paying yourself means you choose the hospital and timing, and pay the provider’s price. Claiming on health insurance means the insurer pays approved costs, subject to your policy terms, excess and limits. If you do not already have insurance, buying it now is unlikely to help with a condition you are already waiting for, because insurers normally exclude conditions that began before cover started. Bupa’s guide to underwriting explains how existing conditions are treated [10].
Paying yourself versus claiming on insurance
What works well
- Self-pay: no approval process; you choose freely.
- Insurance: the insurer pays approved costs.
- Insurance: may include specialist and hospital fees in one claim.
What to watch
- Self-pay: you carry the full cost, which can be large.
- Insurance: existing conditions are usually excluded.
- Insurance: approval, limits and excess apply.
Referrals and approvals
Private consultants usually expect a referral, often from your GP. If you are on an NHS list, your GP can write a private referral using the information they already have. If you are claiming on insurance, contact the insurer before booking anything. It will check your policy, approve the consultation and later the treatment, and may need a referral letter. Booking first and claiming later can lead to refused claims.
Step 1: Speak to your GP
Ask for a private referral to the specialty you need.
Step 2: Contact your insurer, if claiming
Check cover and get approval before booking.
Step 3: Choose a provider
Pick a recognised hospital and consultant.
Step 4: Book the consultation
Book once you have approval or have accepted the self-pay price.
Step 5: Get the treatment approved
If insured, get the treatment itself approved before it is booked.
Using your NHS tests
If you have already had tests or scans on the NHS, ask for copies to be sent to the private consultant. They may avoid the need to repeat them, which saves time and money.
Getting and comparing quotes
If you are paying yourself, ask for itemised written quotes. Check whether the price includes the consultation, tests, surgeon and anaesthetist fees, hospital stay, follow-up and any complications. The Competition and Markets Authority’s work on the private healthcare market led to rules on fee information, so a clear quote is a reasonable request [7]. Our treatment cost guides, such as hip replacement and cataract surgery, show published price examples.
- What exactly is included in the package.
- Which professionals bill separately.
- How complications are handled, and for how long.
- When payment is due, and whether a deposit is needed.
Telling the NHS
Once you have a private date, tell the NHS hospital. Your NHS place for that treatment is usually closed once you have had it privately, and telling them means the place goes to someone else. You keep your entitlement to all other NHS care, under government guidance on mixing NHS and private care [6]. Ask the private consultant to write to your GP after treatment so your records are complete.
Returning to the NHS
If something changes, for example the private consultant recommends a different treatment or the cost becomes too high, you can usually return to NHS care. You may need a new GP referral, and you would join the NHS pathway at that point. Ask your GP how this would work before you leave the NHS list, so you know your options.
The current picture
In August 2026, 7.4 million pathways were waiting in England, with a median wait of 12.2 weeks and 113,339 waiting over a year [9]. Those figures cover every specialty and cannot predict your own wait. Ask your hospital for an expected date before deciding whether switching is worth the cost.
- July 20267.3 m
- August 20267.4 m
The July figure is from NHS England’s September release [1], the August figure from its October release [9].
A decision checklist
| Question | Where to find the answer |
|---|---|
| What is my expected NHS date? | The hospital holding your referral |
| Could another NHS provider see me sooner? | Your GP or the NHS e-Referral Service |
| Am I past or near 18 weeks? | Your referral date, counted forward |
| Will my insurance cover this condition? | Your insurer, in writing |
| What would the private treatment cost in total? | Itemised written quotes |
| How will follow-up work? | The private provider and your GP |
Working through these questions helps you decide whether switching is worth it for you. The Health Guide provides information only and does not give personal advice; if you are thinking of borrowing to pay, consider speaking to a regulated adviser.
If you are claiming on insurance, the FCA’s Consumer Duty expects insurers to help customers understand their cover [11], so ask for a clear written answer about what is and is not included before treatment.
Timing the switch
When to switch matters as much as whether to switch. If your NHS date is only a few weeks away, paying privately may save little time once you allow for a private consultation, any repeat tests and the private hospital’s own scheduling. If your expected NHS date is many months away, or not yet known, the time saved can be much larger. Ask the private provider how soon they could realistically operate after a first consultation, not just how soon you can be seen.
| Stage | Staying on the NHS list | Switching to private |
|---|---|---|
| First specialist appointment | Already had, or date from hospital | Often within weeks, if available |
| Tests | Arranged by NHS team | May reuse NHS results, or repeat |
| Treatment date | Expected date from hospital | Set with the private hospital |
| Follow-up | NHS team | Private team, then GP |
The table is a framework for questions, not a prediction. Ask the NHS hospital for its expected date and the private hospital for its realistic timetable, then compare the two side by side. If the gap is small, the NHS options above may be the better choice.
If your condition changes while you wait
Whichever route you take, tell your GP if symptoms worsen. Your NHS team can review clinical priority, and a change may affect whether switching still makes sense. Do not delay seeking help because you are planning private treatment.
Finally, be wary of any private provider that pressures you to decide quickly or asks for full payment before you have a clear plan. A reputable hospital will give you time to consider a written quote, explain the risks and benefits of treatment, and tell you how follow-up and complications are handled. If you feel rushed, it is reasonable to pause, ask your GP for a view, and compare at least one other provider before committing any money.
Looking at cover with PremierPMI
PremierPMI is a specialist private medical insurance broker and the publisher of The Health Guide. If you want to talk through what this means for your own cover, you can start there.
Or, if you would rather start here, send an enquiry and PremierPMI will contact you.
Common questions
Can I leave an NHS waiting list and go private?
Should I check NHS options before paying privately?
Can I buy health insurance to skip the NHS waiting list?
Do I need a GP referral to go private?
What happens to my NHS place if I go private?
How do I compare private treatment prices?
Can I go back to the NHS if private treatment is too expensive?
Sources and methodology
- [1] NHS England. “NHS referral to treatment (RTT) waiting times data, July 2026 — Statistical Press Notice”. View source(opens in a new tab)Primary source
- [2] Department of Health and Social Care. “The NHS Constitution for England”. View source(opens in a new tab)Primary source
- [3] Department of Health and Social Care. “Consultant-led treatment: right to start within 18 weeks”. View source(opens in a new tab)Primary source
- [4] NHS. “Guide to NHS waiting times in England”. View source(opens in a new tab)Primary source
- [5] NHS. “Your choices in the NHS”. View source(opens in a new tab)Primary source
- [6] Department of Health. “NHS patients who wish to pay for additional private care”. View source(opens in a new tab)Primary source
- [7] Competition and Markets Authority. “Private healthcare market investigation”. View source(opens in a new tab)Primary source
- [8] NHS England. “Elective recovery: a partnership agreement between the NHS and the independent sector”. View source(opens in a new tab)Primary source
- [9] NHS England. “Statistical Press Notice: NHS referral to treatment (RTT) waiting times data, August 2026”. View source(opens in a new tab)Primary source
- [10] Bupa. “Medical underwriting”. View source(opens in a new tab)Primary source
- [11] Financial Conduct Authority. “The Consumer Duty”. View source(opens in a new tab)Primary source
We cite primary sources wherever possible. Read about our sourcing methodology.
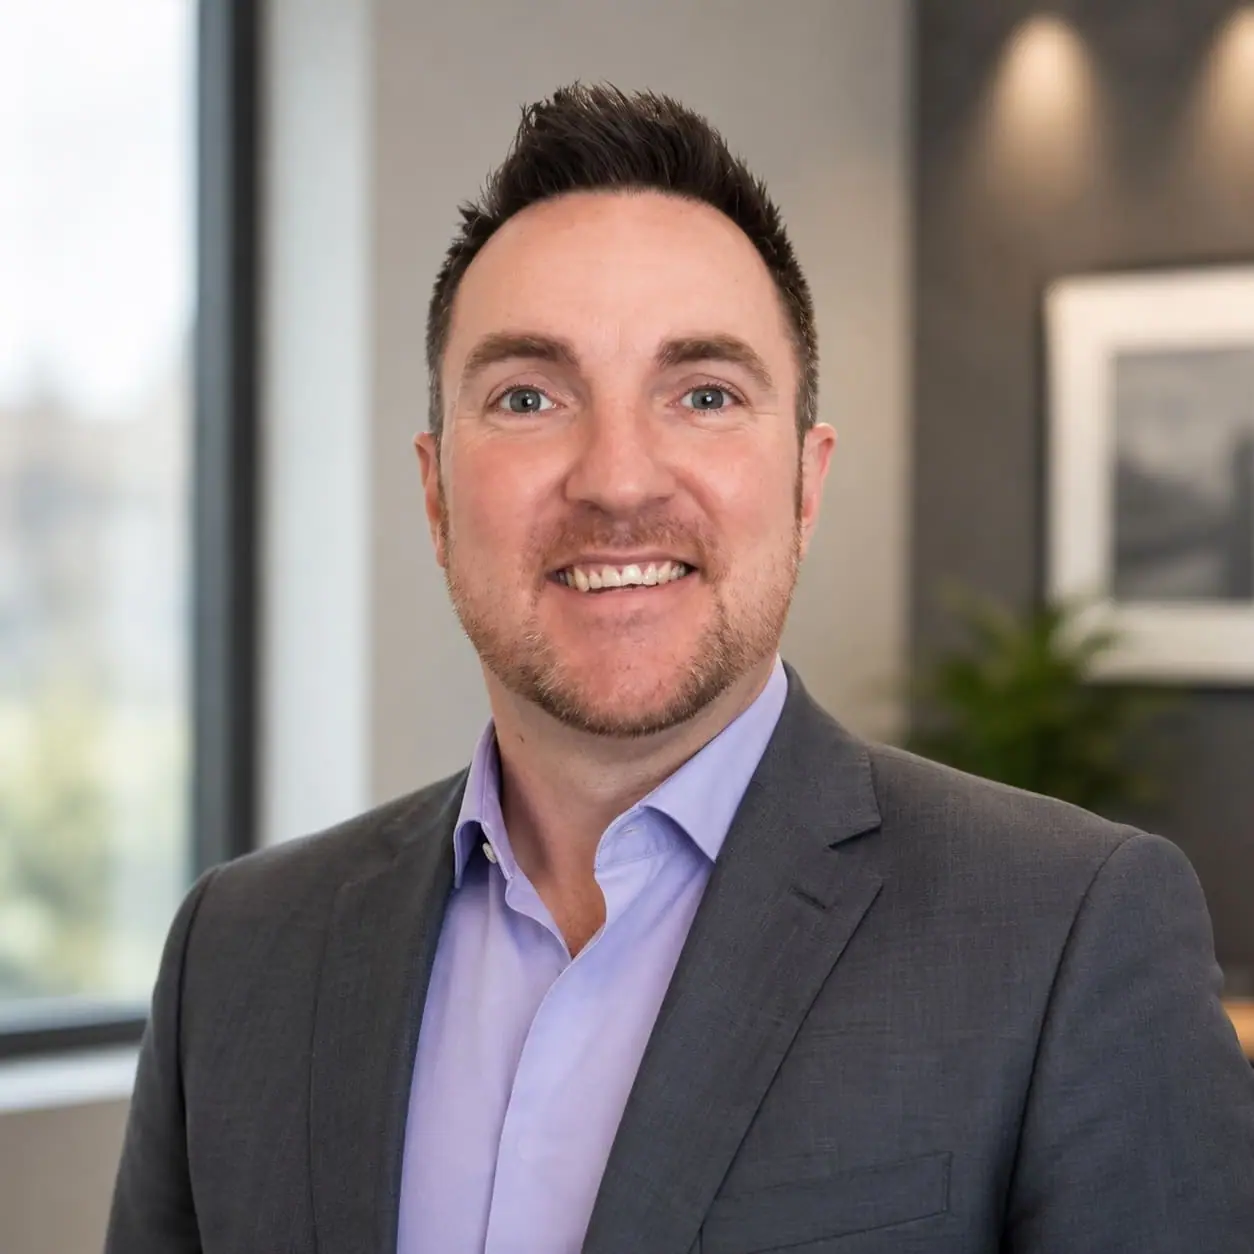
Stuart Hendy
PMI Expert and Head of Publishing, PremierPMI
- 20 years in UK private medical insurance
- Underwriting and corporate placement specialist
Stuart brings over 20 years of experience advising on UK private medical insurance. He is a key member of the private medical insurance team and Head of the Publishing Team, gathering detailed client requirements, liaising with insurers on tailored quotes, and running training on insurer product changes and underwriting nuance.
Read full profile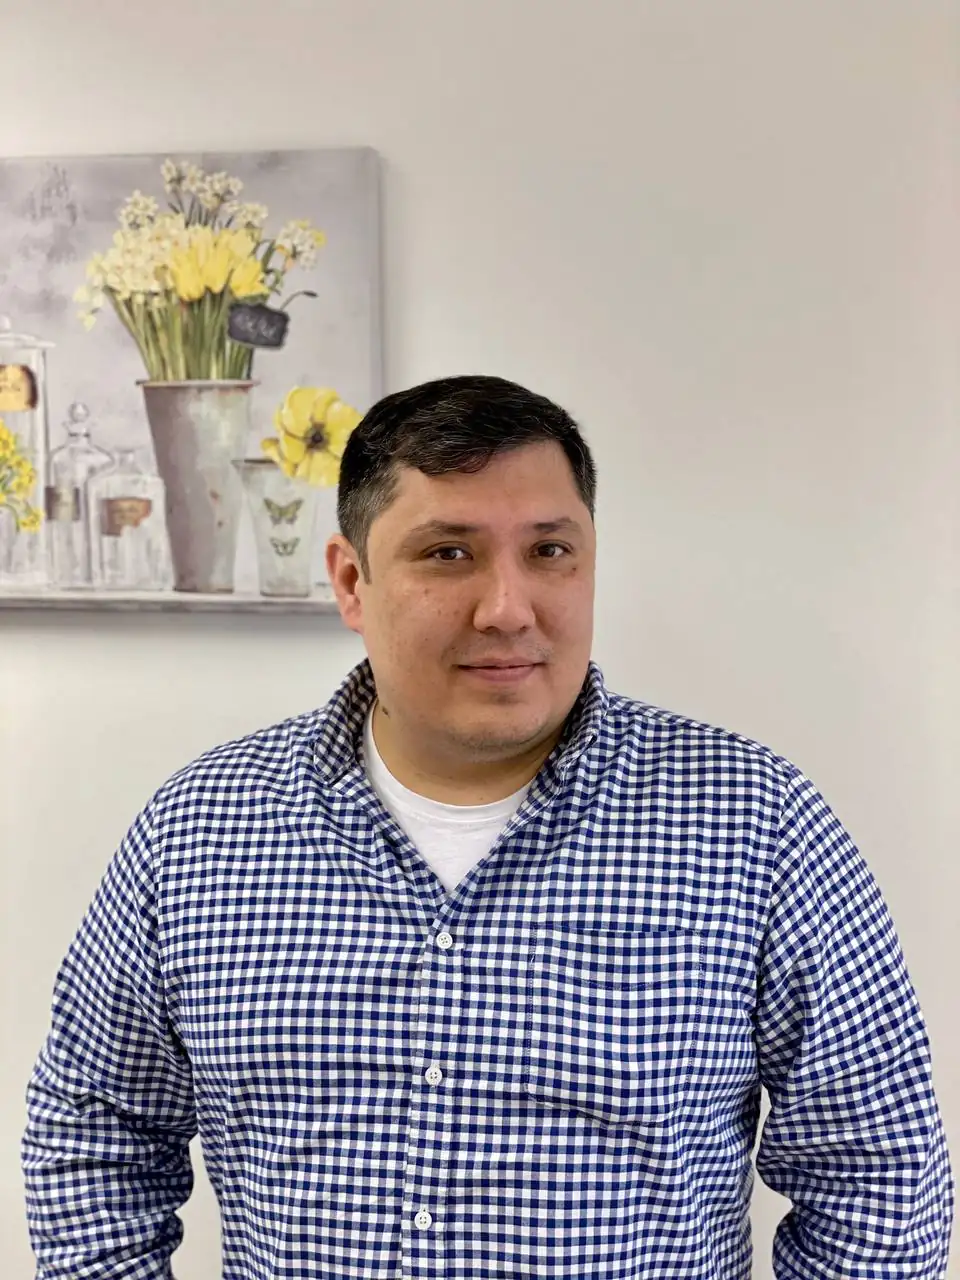
Parvoz Haydarov
Founder, PremierPMI
- Founder of PremierPMI
- Whole-of-market private medical insurance
Parvoz founded PremierPMI as a specialist private medical insurance brokerage. He sets the direction of the firm — insurer relationships, service standards, compliance culture and the editorial bar for everything published under the PremierPMI name — and personally reviews the largest corporate and family cases before they go to market.
Read full profile